Personal Loans in Mississippi: What Licensed Lenders May Charge
Mississippi lets licensed small-loan companies charge some of the highest rates in the country on small balances. Here is how the limits are set, who needs a license, and where to check a lender.
Cap above 36%, by LendCedar Editorial Team Updated 6 minute read
In short
A Mississippi company that makes small consumer loans needs a small loan license under the Small Loan Regulatory Law, Mississippi Code section 75-67-101 and following, from the Department of Banking and Consumer Finance (DBCF). The law's charges fall as the loan grows: the National Consumer Law Center puts the limit at about 59% APR on a $2,000 two-year loan and about 305% on a $500 six-month loan, fees included. The largest loan covered by section 75-67-181(2) is $5,330 from July 1, 2026.
- $2,000 loan cap
- 59% APR
- $10,000 loan cap
- 26% APR
- Small-loan law
- Miss. Code 75-67-101
- Licensed by
- DBCF
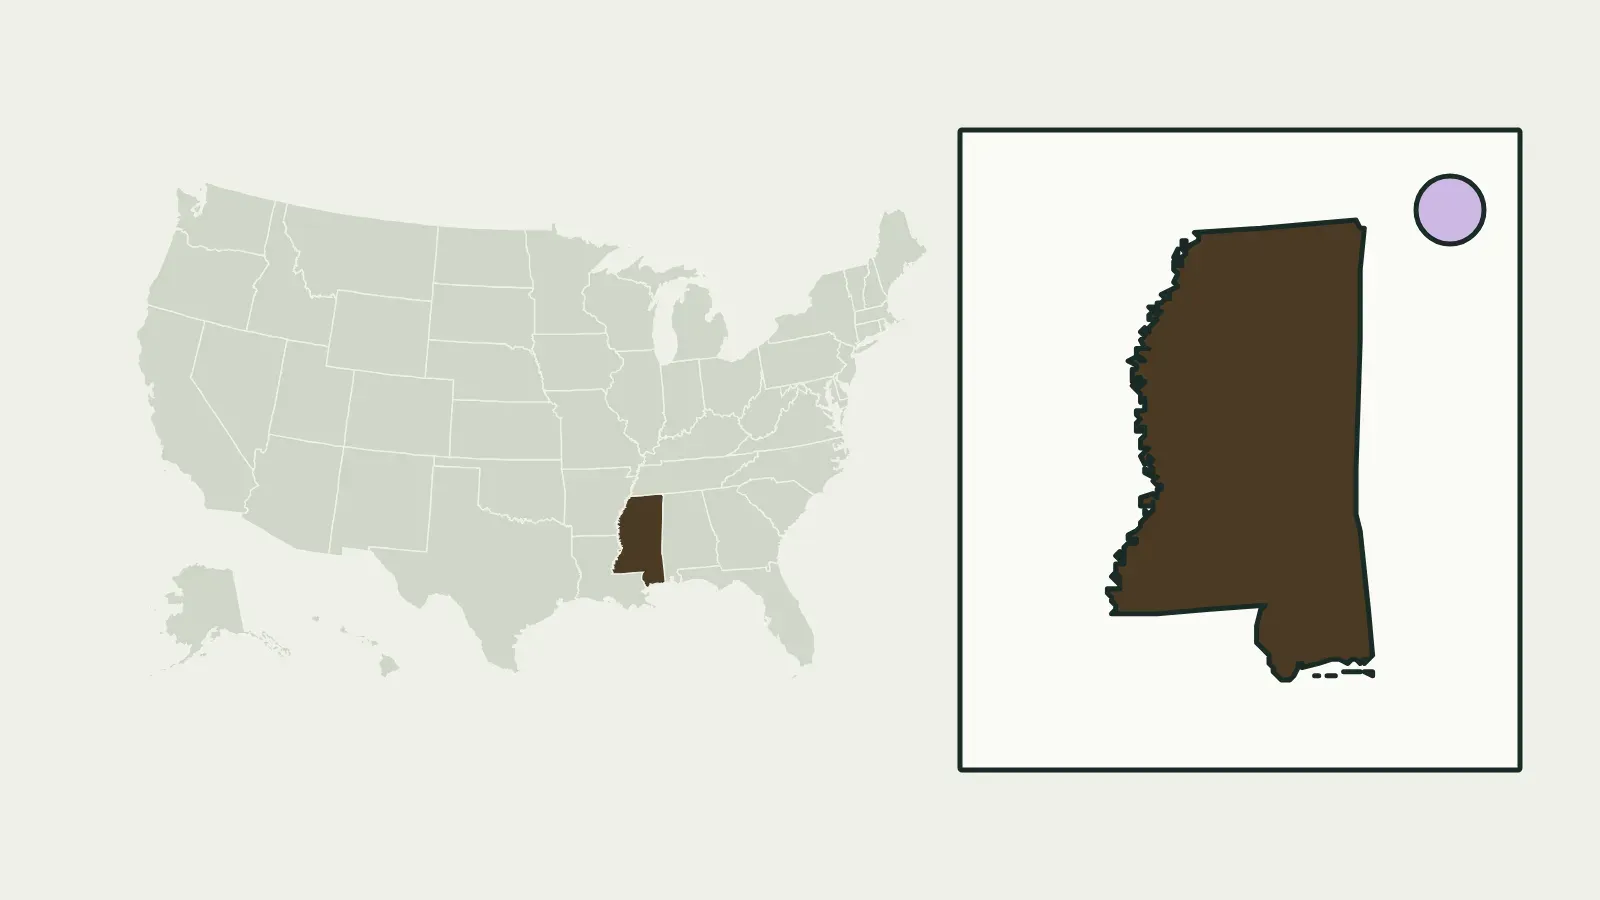
Mississippi at a glance
How the Mississippi rate limit works
The Small Loan Regulatory Law sets the most a licensee may charge, with separate limits that depend on the size of the loan. Small balances carry the highest allowed charges, and the allowed rate drops as the amount borrowed rises. The DBCF also adjusts the maximum loan amount under section 75-67-181(2), described below.
| Example loan | Maximum APR, fees included | Figures as of |
|---|---|---|
| $500 over six months | About 305% | September 2025 |
| $2,000 over two years | About 59% | September 2025 |
| $10,000 over five years | About 26% | August 2023 |
The figures come from the National Consumer Law Center, which compares state caps. They are ceilings, not typical prices: a lender may offer you far less, and a credit union or bank may not use these limits at all. Check the APR on your Truth in Lending disclosure, which counts interest and fees together.
To see what that gap means, take a $2,000 loan repaid in 24 equal monthly payments. At 59% APR the payment is $143.77 and you repay $3,450.48 in all, $1,450.48 of it in finance charges. At 34% APR, the median cap, the payment is $115.98 and the finance charges come to $783.52. These are worked examples, not offers.
The small-loan size limit
Section 75-67-181(2), as amended by the Legislature in its 2024 regular session, sets a maximum loan amount that the DBCF raises with an official memo. For loans from July 1, 2026, the department raised that maximum from $5,220 to $5,330. If you are offered more than that by a small-loan company, ask which law the loan is made under and what rate limit applies to it.
How Mississippi compares with its neighbors
On the National Consumer Law Center's comparison of a $2,000 two-year loan, Arkansas caps the price at about 17% APR, Louisiana at about 38% and Tennessee at about 49%, while Alabama has no numeric cap. Your state of residence and the lender's license decide which rules apply. The state rules map shows every state side by side.
Who needs a license and who does not
The DBCF's Consumer Finance Division licenses and supervises small-loan lenders along with several other credit businesses. A small loan license requires a physical location in Mississippi, and licenses are issued only to locations in the state.
- Other license types cover credit availability lenders, title pledge lenders, check cashers, pawnbrokers and consumer loan brokers. Each follows its own law.
- Banks and credit unions answer to separate charters and regulators. An out-of-state bank may charge the rates its home state allows, and an online lender working with a bank may lend under the bank's rules. Ask who the lender of record is.
- Payday and title loans are covered by our sister site Lendmira on its Mississippi lending laws page.
Check a lender and file a complaint
- Find the license in the DBCF's published list of small loan lenders, or search the company in NMLS Consumer Access, before you apply.
- Keep the loan papers: the Truth in Lending disclosure, the agreement and any messages about fees.
- Complain to the DBCF with the complaint form on its website or by phone at 601-321-6901.
- Send a complaint to the CFPB as well if the lender is a bank or a bank partner, or if you are unsure who regulates it.
A request for a fee before approval or funding is a warning sign. How to verify a lender lists the other checks, and where to borrow compares credit unions, banks and finance companies.
Sources
- Department of Banking and Consumer Finance — Consumer Finance Division (statutes, licensee lists, memos)
- DBCF memo: Small loan maximum loan size under Miss. Code section 75-67-181(2), effective July 1, 2026
- DBCF consumer complaint form
- State APR caps for $500, $2,000 and $10,000 installment loans, December 2025 (National Consumer Law Center)
We checked the facts on this page against these sources on October 27, 2026. The maximum small-loan size is raised by DBCF memo; the July 2025 and July 2026 memos are on the department's Consumer Finance page.
Questions people ask
What is the maximum interest rate on a personal loan in Mississippi?
It depends on the loan size. The National Consumer Law Center puts the limit for a licensed lender at about 59% APR on a $2,000 two-year loan and about 305% on a $500 six-month loan, fees included.
What is the largest loan under the Mississippi small-loan rules?
The DBCF set the maximum loan amount under section 75-67-181(2) at $5,330 for loans from July 1, 2026, up from $5,220.
Do the Mississippi limits apply to banks?
No. Banks and credit unions follow their own charters and federal law, and a bank can charge the rate allowed in its home state.
How do I know if a Mississippi lender is licensed?
Check the DBCF small loan lender list or NMLS Consumer Access, or call the DBCF at 601-321-6901. See how to verify a lender.
Ask lenders for real offers
Describe the loan you have in mind. LendCedar passes your request to lenders and loan brokers who may contact you with offers; you compare them and decide.
- The loan you have in mind: amount, purpose, credit and income.
- Your contact details and your consent to be contacted.
- A lender or loan broker may contact you with an offer. Nothing is decided until you sign with a lender.
LendCedar is not a lender or a loan broker and does not make credit decisions.
You pay LendCedar nothing. Lenders and loan brokers pay us for requests, and they set their own rates and terms. How we make money.
Nearby in the guide
-
Offer term
Total cost of a loan
Finance charge, APR and total of payments, with three worked offers for the same $10,000 loan.
-
Step
Verify a lender
Find the license on NMLS or with your state, match the lender of record and spot advance-fee scams.
-
Step
Where to borrow
Banks, credit unions, online lenders, CDFIs and finance companies: who regulates each and what they may charge.