Personal Loans in Wisconsin: What Licensed Lenders May Charge
Wisconsin sets no maximum interest rate for licensed consumer lenders. The law instead requires a license above 18%, limits some fees and protects your right to pay early. Here is what that means and where to check a lender.
No numeric cap, by LendCedar Editorial Team Updated 5 minute read
In short
A company that makes consumer loans in Wisconsin with a finance charge above 18% a year needs a license from the Division of Banking of the Department of Financial Institutions (DFI) under Wis. Stat. § 138.09. Once licensed, it faces no maximum interest rate: the statute says a loan made after October 31, 1984 is not subject to any rate limit. The National Consumer Law Center lists Wisconsin as having no numeric cap, only an unconscionability standard. The price you are offered is set by the lender, so comparing APRs matters more here than in most states.
- $2,000 loan cap
- No numeric cap
- $10,000 loan cap
- No numeric cap
- License needed above
- 18% finance charge
- Licensed by
- DFI
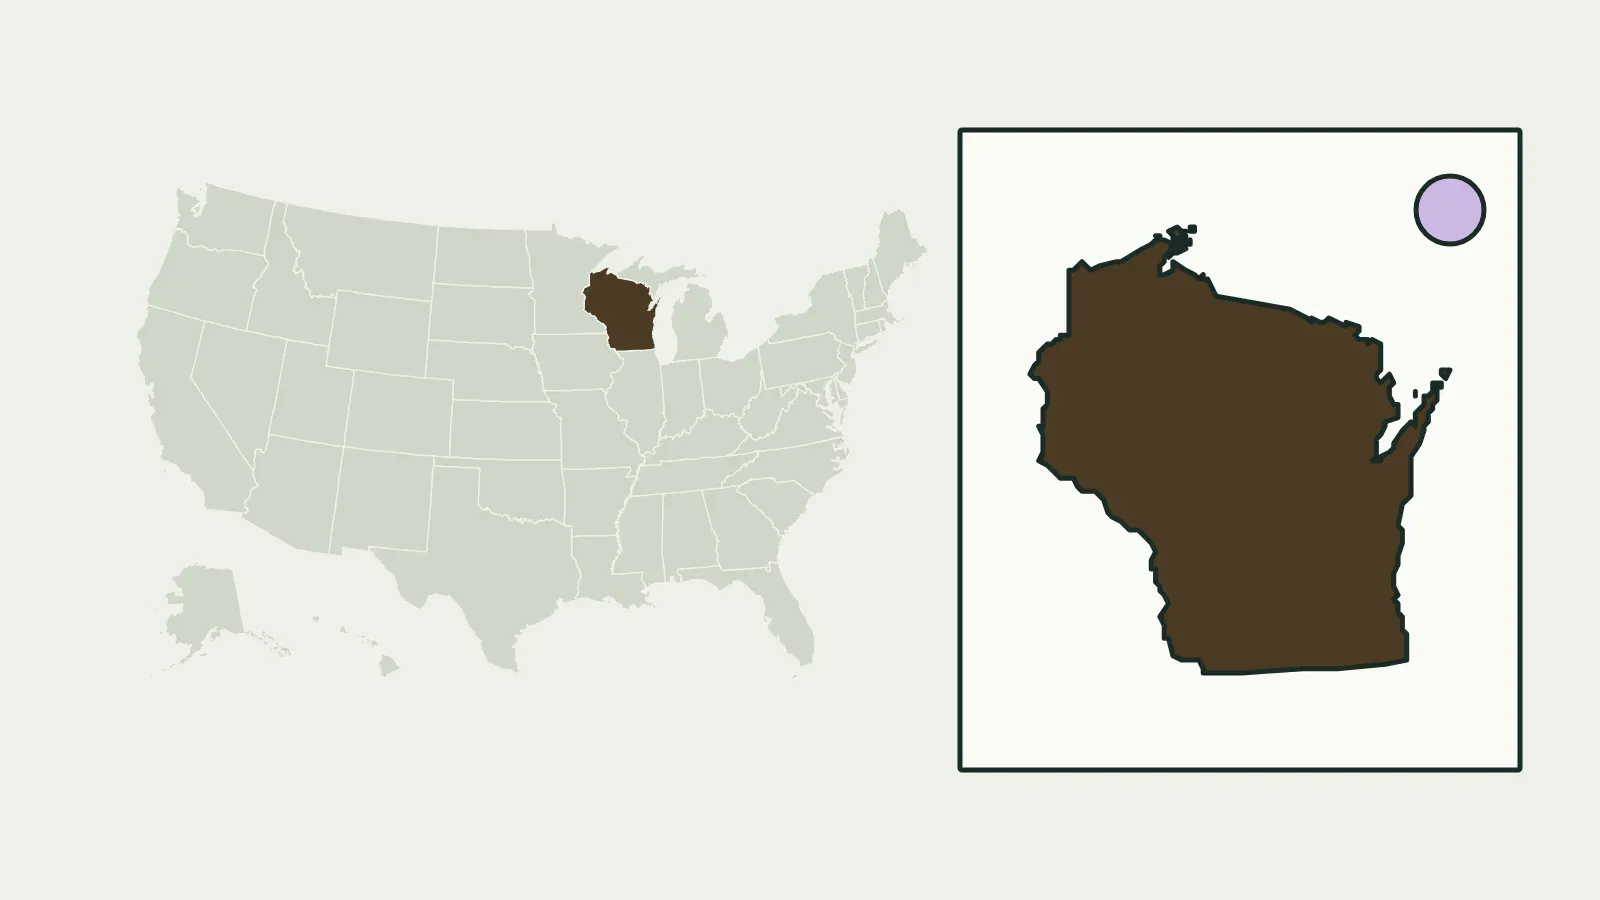
Wisconsin at a glance
How Wisconsin limits loan prices without a cap
Wis. Stat. § 138.09(7)(bp) says a loan made by a licensee after October 31, 1984, precomputed or figured by the actuarial method, is not subject to any maximum interest rate limit. The statute still controls some of the charges around the interest.
| Item | Rule |
|---|---|
| Interest | No maximum rate |
| Prepaid finance charge, amount financed $500 or less | Lesser of 10% or $50 |
| Late charge, precomputed loan | Up to 5% of the installment, after 10 days, once |
| Paying early | Allowed in whole or in part |
With no ceiling, the APR on your Truth in Lending disclosure is the only way to see what an offer costs. Two licensed lenders can quote very different prices for the same $2,000 loan, and both can be legal. Ask each lender for the APR, the finance charge and the total of payments for the same amount and term, then compare them side by side. A lower monthly payment over a longer term can still cost more in total, so look at the total of payments as well as the APR before you choose.
How Wisconsin compares with its neighbors
On the NCLC comparison of a $2,000 two-year loan, every neighbor sets a numeric cap: Michigan about 30% APR, Minnesota 33%, and Illinois and Iowa 36%. Your state of residence and the lender's license decide which rules apply, not where the lender is based. The state rules map shows every state side by side.
Who needs a license and who does not
Under § 138.09, a person must get a license from the Division of Banking before making consumer loans with a finance charge above 18% a year, taking assignments of such loans or collecting on them directly. Licensees must register with the nationwide multistate licensing system (NMLS) and keep a unique identifier there. The section was renumbered and amended by 2023 Wisconsin Acts 131 and 267, with changes taking effect on September 1, 2024 and January 1, 2025.
- Banks, savings banks, savings and loan associations, trust companies and credit unions, and their affiliates, are outside § 138.09, and a bank may charge the rates its home state allows.
- Online lenders that partner with a bank may make loans through that bank. Ask who the lender of record is, since that decides which state's rules and which regulator apply to your loan.
- Prepayment: a licensee must let you pay the loan in whole or in part before it is due, and on full prepayment you get a rebate of unearned interest under the rules in § 138.09(7).
- Payday and title loans are a separate subject. Our sister site Lendmira covers them on its Wisconsin lending laws page.
If a lender asks for a fee before it will approve or fund the loan, treat it as a warning sign; how to verify a lender explains what to check.
Check a lender and file a complaint
- Look up the license in the DFI's Licensed Financial Services licensee search or NMLS Consumer Access before you apply.
- Compare APRs from at least two or three lenders, including a credit union, since no cap limits the price.
- Keep the loan papers: the Truth in Lending disclosure, the agreement and any messages about fees.
- Complain to the DFI with its online complaint form or by phone at (608) 261-9555, Monday to Friday, 7:45 a.m. to 4:30 p.m.
- Send a complaint to the CFPB as well if the lender is a bank or a bank partner, or if you are unsure who regulates it.
Sources
- Wis. Stat. § 138.09 — Licensed lenders (Wisconsin State Legislature)
- Wis. Stat. § 138.09, 2025 edition with subsection (7) (Justia)
- Wisconsin Department of Financial Institutions — complaints and licensee search
- State APR caps for $500, $2,000 and $10,000 installment loans, December 2025 (National Consumer Law Center)
We checked the facts on this page against these sources on October 27, 2026. The licensing section was amended by 2023 Wisconsin Acts 131 and 267; the 2025 edition of the statute still contains the no-maximum-rate rule.
Questions people ask
Is there a maximum interest rate on personal loans in Wisconsin?
Not for licensed lenders. Wis. Stat. § 138.09(7)(bp) says a licensee's loan made after October 31, 1984 is not subject to any maximum interest rate limit. Some fees and late charges are still limited.
Who needs a lender license in Wisconsin?
A person making consumer loans with a finance charge above 18% a year, or taking assignments of or collecting such loans, needs a license from the DFI's Division of Banking. Banks and credit unions are exempt.
Can I pay off a Wisconsin installment loan early?
Yes. A licensee must allow payment in whole or in part before maturity, and on full prepayment you are entitled to a rebate of unearned interest under the statute's rules.
How do I check a Wisconsin lender's license?
Use the DFI Licensed Financial Services licensee search or NMLS Consumer Access. See how to verify a lender for what else to check.
Ask lenders for real offers
Describe the loan you have in mind. LendCedar passes your request to lenders and loan brokers who may contact you with offers; you compare them and decide.
- The loan you have in mind: amount, purpose, credit and income.
- Your contact details and your consent to be contacted.
- A lender or loan broker may contact you with an offer. Nothing is decided until you sign with a lender.
LendCedar is not a lender or a loan broker and does not make credit decisions.
You pay LendCedar nothing. Lenders and loan brokers pay us for requests, and they set their own rates and terms. How we make money.
Nearby in the guide
-
Offer term
Total cost of a loan
Finance charge, APR and total of payments, with three worked offers for the same $10,000 loan.
-
Step
Where to borrow
Banks, credit unions, online lenders, CDFIs and finance companies: who regulates each and what they may charge.
-
Offer term
Prepayment penalties
Simple-interest vs. precomputed loans, the Rule of 78s, and the line that says if early payoff costs extra.